Vietnam's Hotel Pipeline: Where the Next Wave of Rooms is Going, and Who is Building it?
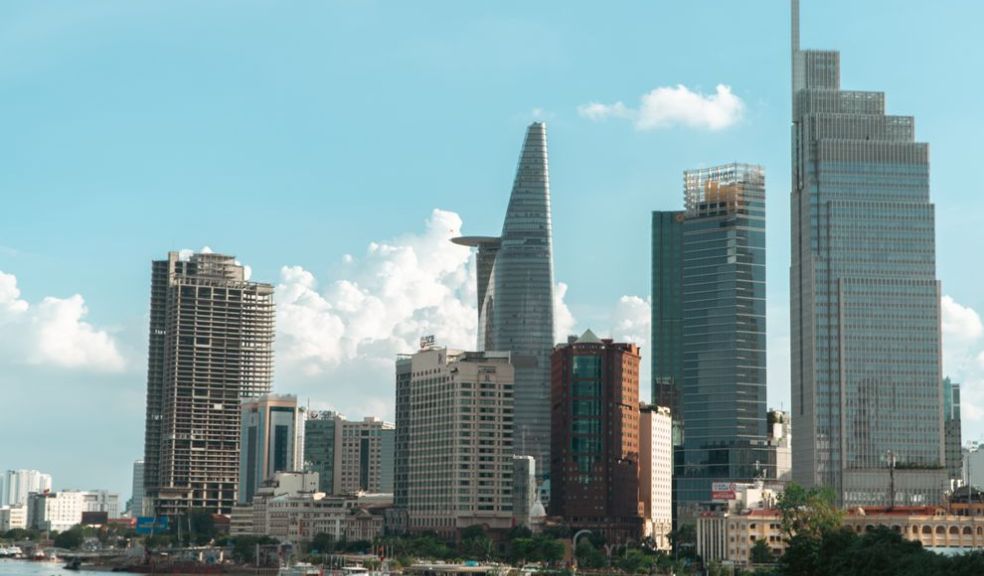
Vietnam's hotel market is running ahead of its supply. In the year to May 2026, room demand rose 14.1% while room supply grew just 2.8%, according to CoStar's national report. Occupancy reached 63.9% and average daily rate US124, against58.4% and about US111 for the whole of 2025. That gap explains why owners and brands are signing deals at pace. It also explains the main risk: the rooms now being built will arrive in a few large waves, in a few places, and at the top end of the market.
CoStar counts 38,354 rooms under construction, about a fifth of the stock in its sample, and 94% of them are upscale or luxury. For anyone underwriting a Vietnamese hotel, a management contract or a residences programme over the next five years, the national numbers matter less than where those rooms land and who is behind them.
Demand has earned the pipeline, so far
International arrivals reached 17.7 million in the first nine months of 2026, up 14.5% year on year. The government's target is 25 million for the year. That would need roughly 2.4 million arrivals a month from October to December, well above September's run rate, so a miss is likely. Even so, the growth is real and broad.
The mix is shifting. Mainland China remains the largest market with about 3.95 million arrivals to September, but it was broadly flat over the first eight months. Russia passed one million arrivals, up more than 160%. India sent more than 670,000 visitors, up 33%, and Vietnam Airlines adds Hanoi–Ahmedabad from 3 November, taking it to seven Vietnam–India routes. Europe as a region grew by more than half in January–August.
Policy is pushing in the same direction. In October the government waived visas for Chinese package-tour groups flying direct into Cam Ranh, the airport for Nha Trang, until the end of 2027. Vietnamese carriers are adding Shanghai, Shenzhen, Moscow, Prague and Almaty. Regional growth is fastest outside the two big cities: accommodation and food revenue rose about 21% in Da Nang and about 20% in both Khanh Hoa and Hue in January–August, according to the national statistics office.
Where the rooms are going
Phu Quoc: one developer, one deadline
No market shows the pipeline risk more clearly than Phu Quoc. The island hosts the APEC Economic Leaders' Meeting in November 2027, and Sun Group plans about 17,400 rooms and serviced apartments there in 2026–27. The island had 26,461 rooms at the end of 2024. If Sun Group delivers on time, Phu Quoc adds the equivalent of about two-thirds of its existing stock in two years, much of it from a single owner that also controls an airline, Sun PhuQuoc Airways, and much of the island's leisure infrastructure.
That vertical integration supports demand: the same group adding rooms is adding seats, including Phu Quoc–Moscow from November. But it leaves independent owners on the island exposed to rate pressure once APEC has passed.
The central coast: Da Nang, Nha Trang and Hoi An
Khanh Hoa and Da Nang already hold more five-star hotels than Hanoi and Ho Chi Minh City combined. Their growth rates lead the country, but both depend heavily on short-haul Asian markets. Korean arrivals to Vietnam fell about 5% to roughly 3.05 million in the first nine months, the only decline among the ten largest source markets. Tour operators blame summer room shortages and higher rates in Da Nang and Phu Quoc. For coastal owners, that is an early warning about price elasticity rather than a collapse in demand.
Hanoi: a policy target for the top end
Hanoi has set a goal of at least 10,000 additional four- and five-star rooms by 2030. The city's rated four- and five-star hotels hold roughly 9,600 rooms today, so the target would about double the top end in five years. At around 2,000 rooms a year, it is broadly in line with the upscale supply Savills expects in 2026. Hanoi also wants 13–15 million international visitors by 2030, against 6.67 million in the first nine months of this year. The demand side of that equation is the harder half.
Ho Chi Minh City and Can Gio
In Ho Chi Minh City, new luxury supply is tied to residential projects. The biggest bet is in Can Gio, the coastal district south of the city. Vingroup's Vinhomes Green Paradise there plans Ritz-Carlton, Marriott and four IHG hotels with Vinpearl. Masterise has a separate Marriott agreement for JW Marriott and Four Points in Can Gio.
Who is building it
Vietnam's pipeline is dominated by a handful of domestic developers, and that shapes its risk profile more than any single brand does.
|
Developer |
Hotel exposure |
What to watch |
|
Vingroup / Vinpearl |
35 hotels, about 17,500 equivalent rooms at end-2025; 62% of leasable rooms managed by Melia or Marriott |
Can Gio delivery and how much rate Vinpearl concedes to fill rooms |
|
Sun Group |
About 17,400 rooms and apartments planned for Phu Quoc in 2026–27; own airline |
Post-APEC occupancy on the island |
|
Masterise |
Marriott deal for four hotels and one branded residence, close to 1,900 keys, including a 231-key Ritz-Carlton in central Saigon |
Residential sales funding hotel build-out |
|
Novaland |
NovaWorld townships in Phan Thiet and Ho Tram; Novotel Phan Thiet targeted for Q1 2027 |
Debt restructuring and a rights issue closing on 29 October |
Two patterns stand out. First, the large groups sign international brands before they build and use them to sell branded residences. Masterise's One Central Saigon, pairing a Ritz-Carlton with 420 residences, is the clearest example. The hotel is often the marketing asset for the residential sale. Second, the international operators are increasingly managers rather than owners. Accor reports the most open hotels in Vietnam of any international group, 45, with Marriott second at 32. Neither carries the balance-sheet risk.
For operators, that is an attractive model. For lenders and minority investors, it means a hotel's timeline can depend more on residential pre-sales and developer refinancing than on hotel demand. Novaland is the cautionary case: NovaWorld Phan Thiet has more than 18,000 units in plan, but fewer than 1,500 had been handed over by the end of 2025.
The risks worth pricing
Concentration. The pipeline is upscale, coastal and clustered. When most of the new rooms sit in the same segment in the same few markets, national occupancy says little about the exposure of an individual asset.
Timing. Event-driven supply, with Phu Quoc and APEC the obvious case, tends to open together and then compete for the same demand once the event has passed.
Source-market swings. The Korean decline shows that Vietnam's coastal resorts can price themselves out of a core market. Growth from Russia and India is welcome, but these markets need different flights, food, timing and distribution.
Developer balance sheets. Several of the largest pipelines depend on groups that fund hotels with residential sales or restructured debt.
The arrivals target. Vietnam will probably finish 2026 below 25 million on current trends. That is still a record year, but plans built on official targets rather than run rates deserve a discount.
What it means for investors and operators
The case for Vietnam remains strong. Demand is growing several times faster than supply, rates are rising and the source-market base is wider than before the pandemic. But returns will diverge sharply by location and timing. Our view: assets in markets with thin local pipelines, such as secondary central-coast cities and Hue, look better placed to hold rate than new luxury rooms in Phu Quoc after 2027. Midscale stock, almost absent from the pipeline, may be the most under-supplied part of the market.
For buyers and brands doing diligence, start with the local pipeline, not the national headline. AsiaHotelier keeps current data on the Vietnam hotel market, including occupancy, rates and supply under construction. The questions to ask are straightforward: who is the developer, what funds the build, when do competing rooms open, and which source markets will fill them.
Sources: CoStar Hospitality National Report Vietnam (updated July 2026); National Statistics Office; Vietnam National Authority of Tourism; Ministry of Culture, Sports and Tourism; Hanoi Programme No. 20; Resolution 325/NQ-CP; company disclosures from Vingroup, Sun Group, Masterise and Novaland.
About the author: AsiaHotelier is a hotel trade publication covering Asia, starting with Vietnam. It publishes news, market data and analysis for hotel owners, investors and operators.